NRI Property Divestment in Gurgaon
A Practical Framework for Sale, Tax Coordination & Repatriation
AERI Insights | NRI Advisory
Selling a property in Gurgaon while living overseas involves considerably more than agreeing a price with a buyer.
For an NRI or eligible overseas property owner, a successful divestment may involve title documentation, buyer qualification, transaction structuring, tax withholding, banking requirements and, where permitted, outward remittance of sale proceeds.
These elements are connected. A documentation issue can affect negotiations. The structure of the transaction can affect tax withholding. Tax compliance can affect banking and remittance. And an overseas seller often has to coordinate all of this without being physically present in India.
AERI approaches such transactions through a structured framework designed to bring the relevant property, transaction and specialist workstreams together.
The objective is not simply to sell the property. It is to create a controlled transaction pathway from asset preparation through closing and post-sale banking coordination.
Who This Guide Is For
This framework is intended primarily for:
- NRIs considering the sale of residential or commercial property in Gurgaon
- Overseas owners who need on-ground transaction coordination
- Sellers who cannot be present in India throughout the transaction
- Families managing inherited or jointly owned property
- Overseas owners considering the movement of eligible sale proceeds outside India
The applicable tax, FEMA, banking and documentation requirements depend on the seller’s circumstances, the property’s acquisition history, the transaction structure and the law applicable to the relevant transaction date.
This article is an operational advisory framework, not legal, tax, FEMA or banking advice.
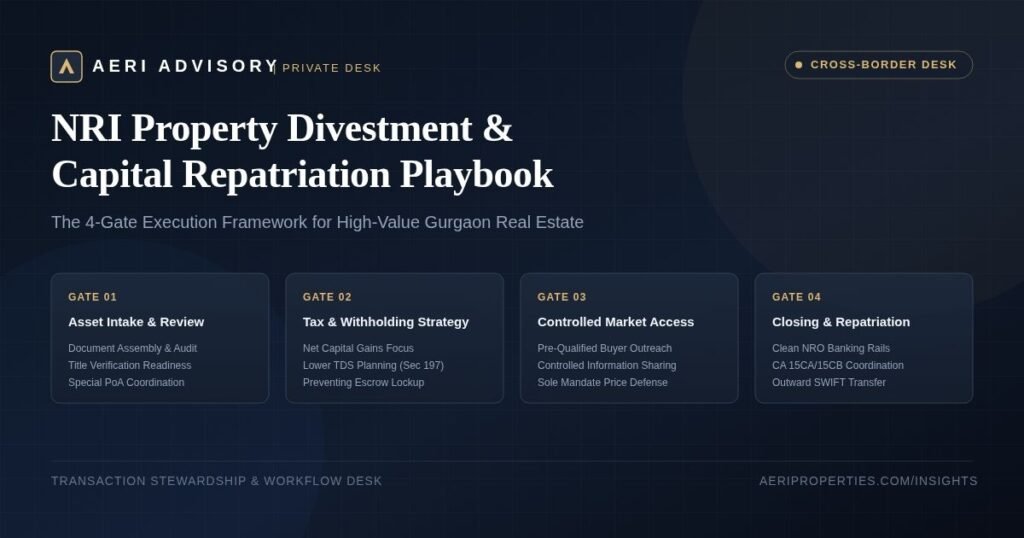
The Four-Gate Execution Framework
AERI’s approach can be viewed through four connected gates:
01 — ASSET & DOCUMENTATION
Establish what is being sold and whether the transaction file is ready.
02 — TAX & TRANSACTION STRUCTURE
Coordinate the withholding and transaction requirements before execution.
03 — CONTROLLED MARKET EXECUTION
Position the property, qualify demand and manage negotiation.
04 — CLOSING & REPATRIATION
Coordinate closing, tax records, banking documentation and any permitted outward remittance.
Each gate has a different purpose. Together they create a more disciplined transaction pathway.
Gate 1 — Asset Intake & Documentation Review
Before exposing a property to the market, the seller’s documentation should be assembled and reviewed.
The objective is not to provide a legal title opinion through AERI. It is to identify the documentation required for the transaction and ensure that the appropriate legal professionals can review the file efficiently.
The Title & Documentation File
Depending on the property and its history, the transaction file may include:
Root & Ownership Documents
- Allotment documentation
- Builder-Buyer Agreement or equivalent agreement
- Registered Conveyance Deed / Sale Deed
- Relevant transfer or assignment documents
- Previous ownership documents where required for title review
Revenue & Municipal Records
- Mutation / revenue records where applicable
- Property tax records
- Relevant municipal or authority records
- No-dues documentation where applicable
Association & Property Records
- Maintenance clearance
- RWA / condominium documentation where applicable
- Electricity and other relevant utility settlements
- Possession and occupation-related documentation where applicable
Financing & Encumbrances
If the property is mortgaged, the transaction should also account for:
- Outstanding loan statement
- Lender’s list of documents held
- Loan closure requirements
- Release of original title documents
- Coordination of payment and release mechanics
The precise documentation required will depend on the property, title history, authority involved and advice of retained legal counsel.
Power of Attorney for Overseas Sellers
An overseas seller who cannot attend the transaction in India may, where legally permissible, use an appropriately drafted and executed Specific Power of Attorney.
This should not be treated as a standard administrative document.
The scope, execution method, authentication, stamping, adjudication and registration requirements should be confirmed before execution with retained legal counsel and the relevant registering authority.
AERI’s operating principle is therefore straightforward:
Use a transaction-specific instrument, properly reviewed by qualified counsel, rather than relying on a generic or unnecessarily broad Power of Attorney.
The precise procedure can vary according to the seller’s location, document, transaction and applicable local requirements.
Gate 2 — Tax & Transaction Structure
For an NRI property sale, tax withholding requires particular attention.
Under the Income Tax Act, 2025, the TDS framework was reorganised from the earlier Income Tax Act, 1961. Section 393 contains the principal TDS provisions for specified payments, including relevant non-resident payments, while the lower/nil deduction certificate provisions are now contained in Section 395(1). (Income Tax India)
Accordingly, an older transaction may still involve references to Sections 195 and 197 of the Income Tax Act, 1961, whereas transactions governed by the new Act should be assessed under the corresponding provisions of the 2025 Act.
Why the withholding position matters
The amount withheld at source can have a significant effect on the seller’s immediate liquidity.
The appropriate withholding position should therefore be determined before the transaction becomes unconditional, rather than treated as an administrative matter after completion.
A retained Chartered Accountant should assess:
- Nature and holding period of the asset
- Capital gain computation
- Acquisition cost and eligible costs
- Applicable tax rate
- Surcharge and cess, where applicable
- Relevant exemptions or reliefs
- DTAA considerations, where applicable
- Appropriate withholding requirement
- Whether a lower/nil deduction certificate should be considered
For qualifying long-term capital gains, the applicable base rate may be 12.5%, but the actual tax and withholding position depends on the facts and provisions applicable to the transaction. The Income Tax Department’s current material confirms 12.5% treatment for relevant non-resident long-term capital gains. (Income Tax India)
Lower / Nil Withholding
Where the facts support it, the seller’s CA may consider an application for a lower or nil withholding certificate.
Under the Income Tax Act, 2025, the corresponding provision is Section 395(1). (Income Tax India)
This should be treated as a tax-planning and compliance workstream led by the retained CA, not as an AERI tax opinion.
The 2026 Form Transition
A particularly important consideration for current transactions is the transition from the Income Tax Act, 1961 to the Income Tax Act, 2025.
For remittances made on or after 1 April 2026, the Income Tax Department confirms that the new framework applies and that:
- Form 145 replaces the earlier Form 15CA
- Form 146 replaces the earlier Form 15CB
Form 145 is the remitter’s information/declaration form, while Form 146 is the Chartered Accountant’s certificate in applicable cases.
The Income Tax Department also confirms that the new framework retains broadly similar thresholds and substantive requirements, while changing the statutory forms and structure.
Therefore:
Do not assume that an older transaction checklist remains current simply because the underlying process looks familiar.
The CA handling the transaction should confirm the applicable forms and provisions based on the transaction and remittance dates.
Gate 3 — Controlled Market Execution
Once the documentation and transaction framework are sufficiently clear, the property can be positioned for the market.
For an overseas seller, uncontrolled exposure can create unnecessary complexity.
AERI’s approach is based on controlled information sharing and qualified market access.
Stage 1 — Property Brief
A concise property brief can establish:
- Micro-market
- Project / building
- Configuration
- Area
- Floor band
- Property condition
- Possession / occupancy status
- Indicative pricing
- Relevant commercial parameters
At this stage, information should be sufficient to assess the opportunity without unnecessarily circulating sensitive ownership or property-identification details.
Stage 2 — Qualified Buyer Engagement
Where appropriate, AERI can progressively disclose additional information after assessing:
- Genuine buyer interest
- Financial capability
- Transaction fit
- Timing
- Funding structure
The exact disclosure process should be determined by the mandate and seller’s requirements.
Stage 3 — Negotiation
AERI’s role is to provide commercial coordination around:
- Buyer qualification
- Price discovery
- Offer comparison
- Commercial negotiation
- Transaction conditions
- Timelines
- Coordination with legal and tax professionals
The objective is not simply to maximise the headline number.
It is to assess the quality and certainty of the overall transaction.
Clean Transaction Rails
AERI does not participate in:
- Cash side-adjustments
- Under-invoicing
- Off-book consideration
- Undocumented rebates
- Informal settlement structures
All consideration should be properly documented and routed through appropriate banking channels.
Such arrangements can create significant tax, FEMA, regulatory and legal risks and may complicate the ability to document or repatriate funds.
Clean transaction rails are a non-negotiable part of AERI’s operating approach.
Gate 4 — Closing, Banking & Repatriation
Registration of the sale does not necessarily end the operational process for an overseas seller.
After closing, the seller may still need to coordinate:
Sale completion
↓
Receipt of sale consideration through the appropriate Indian banking channel
↓
Tax reconciliation and TDS credit verification
↓
CA / tax documentation
↓
Bank compliance review
↓
Permitted outward remittance, where applicable
The precise banking route depends on the seller’s circumstances and the property’s acquisition history.
NRO Accounts & Sale Proceeds
For many NRI property transactions, the NRO account is an important part of the banking structure.
However, the appropriate account and repatriation route should not be assumed without reviewing:
- How the property was originally acquired
- Whether acquisition was funded through foreign exchange
- Whether funds came from NRE / FCNR / NRO sources
- Whether the property was inherited
- Whether the seller’s circumstances have changed
- Applicable FEMA/RBI requirements
The relevant RBI framework distinguishes between assets acquired through foreign exchange and assets acquired through rupee funds, inheritance or other permitted routes.
The USD 1 Million Repatriation Facility
Eligible NRIs/PIOs may, subject to applicable FEMA/RBI conditions, documentation and tax compliance, use the USD 1 million per financial year remittance facility in specified circumstances involving NRO balances, sale proceeds of assets and inherited/legacy assets.
This should not be interpreted as an unconditional entitlement to repatriate every property-sale amount.
The applicable route depends on the nature and acquisition history of the asset.
Where immovable property was acquired in accordance with foreign-exchange regulations using foreign exchange or qualifying NRE/FCNR funds, RBI rules can provide a separate repatriation route subject to prescribed conditions, including limits linked to the amount originally paid and, for residential property, restrictions relating to the number of properties.
Therefore, the correct question is not:
“Can an NRI repatriate the sale proceeds?”
It is:
“What portion of the sale proceeds is eligible for repatriation, through which route, and subject to which FEMA, tax and banking conditions?”
That determination belongs with the seller’s CA and Authorized Dealer bank.
The Repatriation Documentation File
Depending on the transaction, the bank and CA may require documentation such as:
- Registered Sale Deed
- Proof of acquisition
- Bank statements
- Evidence of receipt of sale consideration
- TDS documentation
- Applicable CA certification
- Applicable remittance declaration
- Form A2
- FEMA-related declarations
- Other documents requested by the AD bank
For remittances under the current tax framework, Form 145 and, where applicable, Form 146 form part of the tax documentation process.
The Authorized Dealer bank remains responsible for its own compliance and document requirements.
A Practical Transaction Checklist
| Stage | Key Workstream | Primary Responsibility |
|---|---|---|
| 1. Intake | Property & ownership documentation | Seller + AERI |
| 2. Legal Review | Title / PoA / contractual review | Retained Legal Counsel |
| 3. Tax Review | Capital gains & withholding position | Retained CA |
| 4. Market Preparation | Pricing & controlled outreach | AERI + Seller |
| 5. Buyer Qualification | Financial and transaction assessment | AERI + Buyer |
| 6. Transaction Terms | Agreement, conditions & payment structure | Buyer + Seller + Specialists |
| 7. Registration | Sale deed / registration process | Legal Counsel / authorised representative |
| 8. TDS | Deduction, reporting & credit verification | Buyer + CA |
| 9. Banking | Receipt and account reconciliation | Seller + AD Bank |
| 10. Repatriation | Tax, FEMA & remittance documentation | CA + AD Bank + Seller |
What AERI Does
AERI’s role is to provide property advisory and transaction coordination.
For an NRI divestment mandate, this can include:
- Understanding the seller’s objectives
- Reviewing the property and market context
- Preparing the transaction pathway
- Coordinating property documentation
- Supporting market positioning
- Managing controlled buyer outreach
- Qualifying buyer interest
- Supporting commercial negotiation
- Coordinating transaction milestones
- Working with the seller’s retained legal, tax and banking professionals
- Maintaining on-ground execution discipline
AERI does not replace the client’s:
- Lawyer
- Chartered Accountant
- Tax advisor
- Authorized Dealer bank
- Title professional
- Other regulated specialist
The objective is to make these professional workstreams operate as a coordinated transaction process rather than as disconnected tasks.
AERI’s Professional Scope
AERI Advisory is an independent property advisory and transaction coordination practice.
It is not a law firm, Chartered Accountancy practice, tax practice or foreign-exchange dealer.
Formal legal opinions, title opinions, Power of Attorney drafting, tax computations, withholding certificates, FEMA determinations and remittance certifications must be handled by appropriately qualified professionals.
AERI’s role is to coordinate the property and transaction process with those specialists and keep the overall execution aligned.
The AERI Perspective
For an overseas seller, the biggest challenge is often not finding a buyer.
It is coordinating the transaction correctly from beginning to end.
The property needs to be understood.
The documentation needs to be organised.
The buyer needs to be qualified.
The transaction needs to be commercially structured.
The tax position needs to be addressed before money moves.
And any permitted repatriation needs to pass through the appropriate banking and regulatory framework.
A disciplined process reduces avoidable friction.
It does not eliminate every transaction risk—but it makes the relevant risks visible, organised and manageable.
Final Thought
For an NRI property sale, the transaction does not end with finding a buyer. It ends when the property, documentation, tax, banking and permitted remittance workstreams have been appropriately coordinated.
That is where experienced on-ground transaction management can add value.
AERI Advisory
Independent Gurgaon Property Advisory & Transactions
Start a Conversation →
Regulatory & Professional Note
Last reviewed: 23 September 2026
This article is intended as general educational and operational information. It is not legal, tax, accounting, FEMA, foreign-exchange or investment advice. Rules and procedures can change, and the applicable treatment depends on the facts of each transaction, including residential status, citizenship/OCI status, acquisition history, funding source, property type, transaction date and applicable tax/FEMA provisions.
For a live transaction, the seller should obtain advice from the appropriate qualified legal counsel, Chartered Accountant and Authorized Dealer bank before executing documents or moving funds.
The tax framework referenced above reflects the transition to the Income Tax Act, 2025 from 1 April 2026. The Income Tax Department confirms that Forms 145 and 146 replaced Forms 15CA and 15CB for applicable remittances under the new framework.
RBI’s remittance framework should be checked against the seller’s individual circumstances and the latest instructions applicable to the transaction.